How to Manage Debt with Bad Credit in 2026: A Practical Guide to Consolidation Loans, Interest Rates, and Rebuilding Your Financial Health
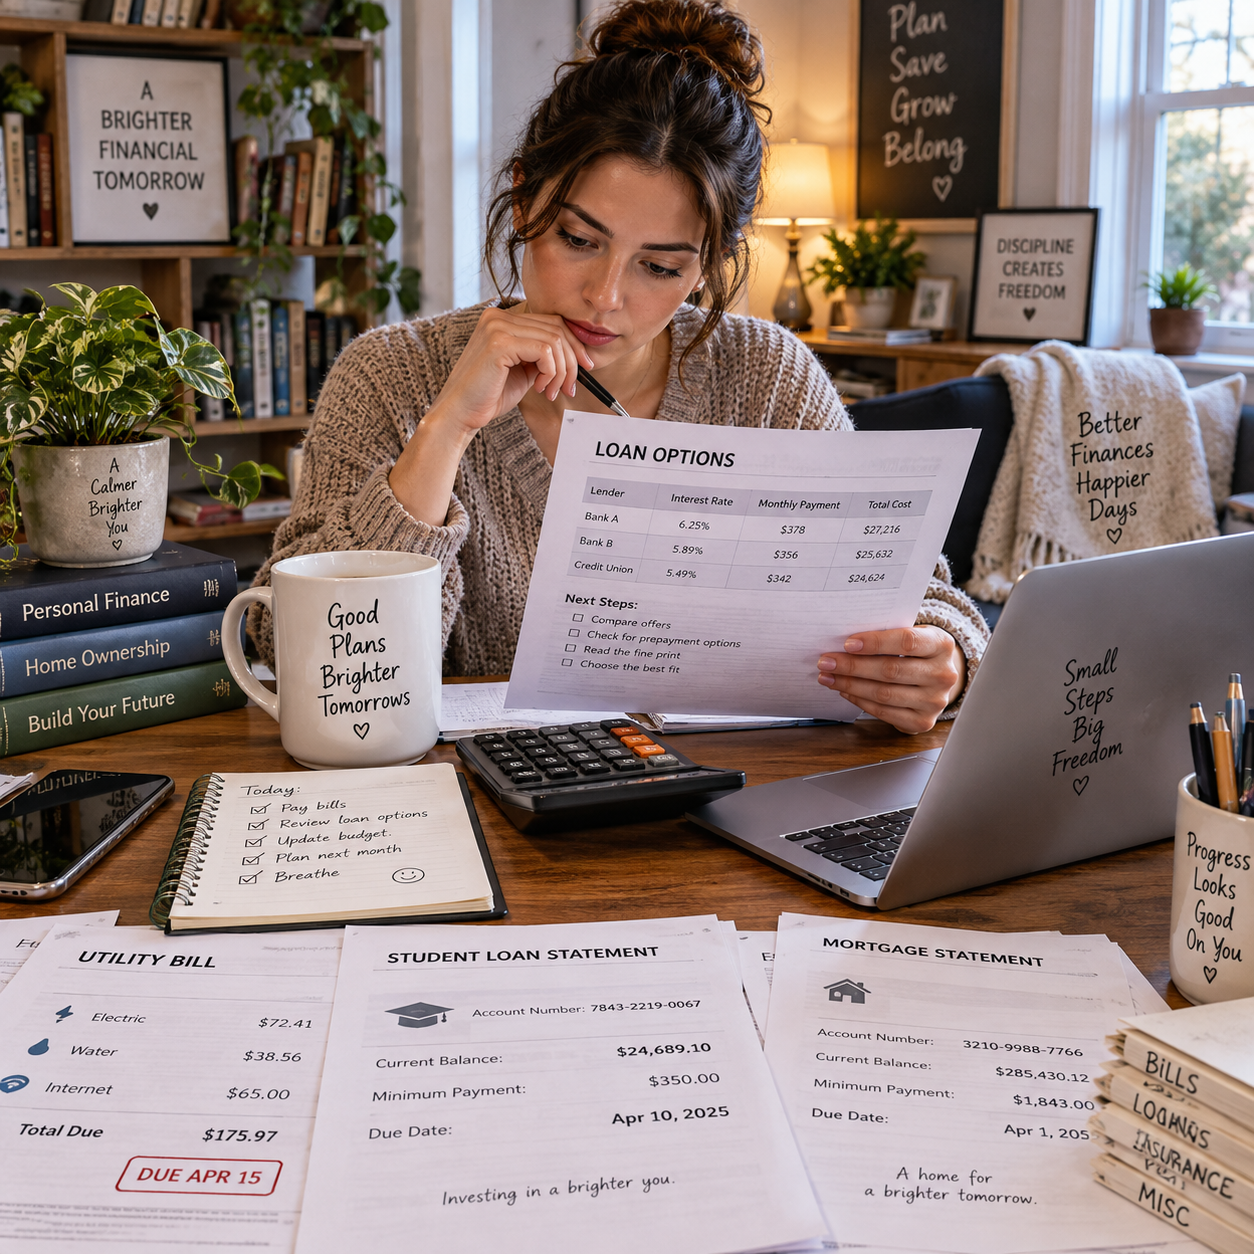
If you're reading this in Italy right now, chances are you already know the feeling: rent or mortgage payments creeping up, a couple of credit card balances that never seem to shrink, and a credit score that makes every phone call from a lender feel like a small interrogation. You're not alone. Rising living costs across the country have pushed more people into juggling multiple debts, and once you miss a payment or two, the label 'cattivo pagatore' starts following you around like a shadow. The good news is that 2026 offers more tools than ever to fight back—debt consolidation loans, smarter interest rate strategies, and a handful of disciplined habits can genuinely turn things around, even if your credit history isn't pristine.
Understanding Bad Credit and Its Impact on Debt Management
In Italy, 'bad credit' isn't just a vague concept—it's a documented status tracked by credit bureaus that lenders check before approving almost anything, from a car loan to a simple credit card increase. Missed payments, defaulted loans, or unpaid installments get reported, and once that happens, your borrowing options narrow considerably. Banks become hesitant, interest rates climb, and sometimes you're asked for a guarantor just to get a modest loan approved. This is the reality that makes debt management so much harder for people who already feel financially stretched.
How Credit Bureaus in Italy Score Your Financial History
Organizations like CRIF, Experian Italia, and CTC (Centrale dei Rischi) collect and share information about your payment behavior across banks and financial institutions. A single 'segnalazione' for a missed installment can stay on your record for years, and a 'protesto' (a formal notice of unpaid debt) is even more damaging. Lenders pull these reports before deciding whether to approve a consolidation loan, and a negative history often means higher interest rates or outright rejection from traditional banks. Understanding this system is the first step toward navigating it more strategically.
What Is Debt Consolidation and Why It Matters
Debt consolidation is essentially taking several separate debts—credit cards, personal loans, an overdraft on your checking account—and rolling them into a single new loan with one monthly payment. Ideally, this new loan carries a lower or at least fixed interest rate compared to what you were paying across multiple accounts. For someone with bad credit, this matters enormously because it simplifies an otherwise chaotic repayment schedule. Instead of tracking five due dates and five different interest rates, you have one predictable payment, which reduces the risk of missing something and falling further into negative credit territory.
Finding the Right Consolidation Loan with Bad Credit
Here's where things get tricky. Lenders naturally see bad credit as a risk signal, so securing a consolidation loan usually means facing higher interest rates, stricter income verification, or requests for a guarantor or collateral. Some Italian banks simply won't consider applicants with recent negative reports, pushing many borrowers toward specialized fintech lenders or credit unions that focus specifically on subprime borrowers.
For readers comparing lenders, exploring the best debt consolidation loans for bad credit can help identify providers that specialize in flexible terms for lower credit scores, offering a useful starting point before approaching Italian banks or fintech lenders. Doing this kind of research upfront saves time and helps you avoid predatory offers that look attractive on the surface but hide steep costs underneath.
Key Factors to Compare Before Signing
- TAEG (APR): This is the true annual cost of the loan, including fees—always compare this number, not just the nominal interest rate.
- Loan term: Longer terms lower your monthly payment but can significantly increase total interest paid over time.
- Prepayment penalties: Check whether you can pay off the loan early without extra fees if your financial situation improves.
- Additional fees: Look for administrative charges, insurance add-ons, or mandatory account opening costs that inflate the real price.
Interest Rates and Hidden Costs to Watch For
In 2026, borrowers with bad credit in Italy typically see TAEG rates noticeably higher than the national average—sometimes double, depending on the lender and the severity of past defaults. Fixed-rate loans tend to be safer for budgeting since your payment never changes, while variable-rate options can start lower but carry the risk of rising over time. Watch closely for bundled insurance policies that lenders sometimes attach to consolidation loans; these can add hundreds of euros to the total cost without providing much real benefit. If you're negotiating, don't be afraid to ask directly whether the rate is negotiable, especially if you can show recent improvement in your income or a stable job situation—lenders do sometimes adjust terms for borrowers who demonstrate reliability, even with an imperfect credit file.
Practical Steps to Rebuild Credit While Repaying Debt
Consolidating your debt is only half the battle—the other half is rebuilding your credit standing so future borrowing becomes easier and cheaper. A few practical habits make a real difference:
- Set up automatic payments so you never miss a due date, since payment history is the single biggest factor in your credit score.
- Use a budgeting app to track spending in real time and catch problems before they become new debts.
- Avoid opening new high-interest credit lines while you're still paying off your consolidation loan.
- Check your CRIF or Experian report periodically to make sure old debts are correctly marked as resolved once paid.
Building an Emergency Fund Alongside Debt Repayment
It might sound counterintuitive to save money while you're still in debt, but even a small emergency fund—say, 500 to 1,000 euros—can prevent you from reaching for a credit card the next time your car needs repairs or an unexpected bill shows up. Without that cushion, one surprise expense can undo months of careful repayment progress and push you right back into the debt cycle you're trying to escape.
Common Mistakes to Avoid When Consolidating Debt
One of the most frequent errors I see is people stretching their loan term way out just to shrink the monthly payment, without realizing that doing so often means paying significantly more in total interest over the life of the loan. Another common mistake is skimming past the fine print—missing details about variable rate clauses or early repayment fees that only surface later. And perhaps the biggest trap of all is consolidating debt without actually changing the spending habits that created the problem in the first place. A consolidation loan buys you breathing room, but it doesn't fix underlying budget issues on its own.
Managing debt with bad credit in Italy in 2026 is genuinely achievable, but it requires informed choices rather than quick fixes. Comparing rates carefully, understanding what lenders are really offering, and sticking to consistent financial habits are what turn a consolidation loan from a temporary patch into a lasting solution. If you're ready to take the first step, start by researching reputable lenders, reading the terms closely, and committing to a repayment plan you can realistically sustain—your credit score, and your peace of mind, will thank you for it.